Higher oil prices can improve Nigeria’s export earnings while making daily life more expensive. The same barrel that supports dollar receipts also raises the cost of the crude used to produce petrol and diesel. For investors entering the fourth quarter, the important question is where those gains and costs land.
The US Energy Information Administration’s September 2026 outlook put August’s average Brent spot price at $91 a barrel, $7 higher than July. Its forecast, completed on 3 September and released on 9 September, expected an average around $90 for the second half of 2026. These are a historical monthly average and a dated forecast, not an oil-price quotation for 2 October.
On the supply side, the Nigerian Upstream Petroleum Regulatory Commission reported on 13 September that August crude and condensate production averaged 1,677,777 barrels a day, up 0.4% from July. Crude alone was 1,500,190 barrels a day. Keeping those two series separate matters when comparing production with crude-only targets.
A stronger oil price needs barrels that can be sold
The first transmission channel is upstream revenue. With other factors unchanged, higher realised prices increase receipts on barrels sold. But a production number is not an export-sales number, and gross sales are not the government’s net revenue.
Domestic deliveries, ownership shares, contractual entitlements, costs, taxes and collection timing all sit between headline output and fiscal cash. A calculation that multiplies all Nigerian production by Brent and labels the answer government income would skip most of that accounting. Nigerian crude grades can also trade at premiums or discounts to the benchmark.
Operational reliability remains central. NUPRC attributed August’s modest improvement largely to the resolution of Single Buoy Mooring problems at the Erha field. Higher global prices cannot compensate fully for barrels that are unavailable because evacuation infrastructure is constrained or an asset is shut down.
For a listed producer, the useful combination is therefore realised selling price, production available for sale, lifting costs, capital expenditure and financing commitments. Stronger revenue can coexist with weak free cash flow if maintenance, development spending or debt service absorbs the increase.
Our analysis of Seplat’s ownership change and half-year operating figures applies those checks to a listed producer, separating the share transaction from the company’s production and cash generation.
The household channel runs in the opposite direction
Reuters reported on 21 September, in a dispatch republished by Polity, that petrol in Lagos and Abuja was selling at about ₦1,400 a litre, against roughly ₦1,200 a month earlier. Those were Reuters’ checks at that time, rather than a national average or a verified pump price today.
Fuel costs reach consumers through several routes. Transport operators may raise fares; distributors face higher delivery bills; businesses using generators pay more to maintain operations. Some companies pass the increase through immediately. Others absorb it in margins, reduce service or wait until existing inventories have been sold.
Domestic refining can reduce reliance on imported finished products and change freight, storage and supply-chain costs. It does not remove the economic value of the crude entering a refinery. Whether purchased locally or abroad, feedstock still carries a cost, and refined-product prices are influenced by the wider market.
The exchange rate adds another layer. A stronger naira can offset part of a dollar-priced input increase, while depreciation can compound it. The size and timing of that offset depend on procurement terms, currency exposures and inventories. There is no dependable one-for-one relationship between a daily Brent move and the next petrol-price adjustment.
Translate the oil shock into company-specific questions
An upstream producer, a fuel distributor and a consumer-goods manufacturer have different exposures. Distributors may need more working capital to carry the same physical inventory. Manufacturers must judge how much of an energy-cost increase customers can absorb. Exporters may have dollar receipts that provide a partial natural hedge against imported inputs.
In each case, watch volumes and cash conversion alongside reported naira revenue. Inflation can lift nominal sales even as customers buy fewer units. A larger inventory balance can support future sales or signal that more cash has become trapped in the operating cycle.
Nigeria’s aggregate oil benefit will ultimately depend on export volumes, realised prices and the flow of receipts into the wider economy. The cost side depends on fuel pricing, currency movements and business responses. September’s evidence makes both channels relevant. Treating a higher crude price as an uncomplicated gain for every Nigerian asset would miss the pressures building elsewhere in the same economy.
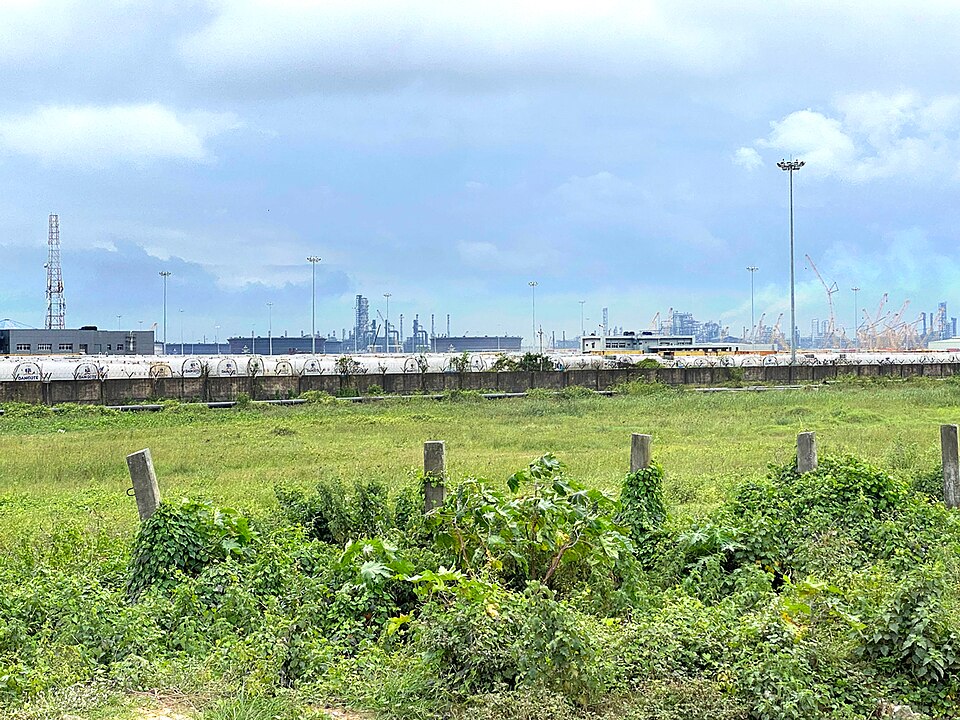
Image: Dangote refinery, Lagos, Nigeria. Photograph uploaded September 2026. Photo by FrankvEck / Wikimedia Commons, licensed CC BY-SA 4.0. Wikimedia-provided 960px rendering; no local visual edits.
